
It is now pretty widely reported that luxury sales, particularly ‘soft luxury’, have cooled off from the breakneck growth experienced during the industry-wide super cycle that followed the pandemic. Some of the industry’s biggest names are reporting some historically bad numbers. However, industry averages (or medians) mask another trend: a sharp increase in performance differentiation across luxury brands and product categories. If you like, average growth is slowing but the standard deviation of the industry’s performance is rising. There are some losers but also some remaining winners.
Let’s start by identifying which brands continue to win with consumers. Here, we looked at a large sample of earnings reports, readily available on company websites for public companies, for luxury fashion, jewelry, watches, cosmetics, and fragrance brands. We are excluding some other major verticals, such as eyewear, travel and wellness, and automobiles, for several reasons. In many cases, these brands have characteristics that make comparison with others in our sample difficult, and we can conduct a separate analysis later on that relies less on large-sample (Large-N) comparisons at a later stage.
Below we show annual revenue growth for the period of April to June 2025. (You can find our analysis for the full year 2024 and January to March 2025, which provides a similar comparison.) We cover 24 different public brands or quasi-brands. As LVMH and Richemont do not report individual brand data separately, we pulled out some high-level product categories that are reported: LVMH watches and jewelry, LVMH perfumes and cosmetics, LVMH fashion and leather goods, Richemont jewelry, and Richemont specialist watchmakers. This results in something different than a pure apples-to-apples comparison with the other brands (which themselves may be a mix of different types of products), but this is better than nothing and seems necessary given that LVMH and Richemont represent around 35 and 10 percent of the industry, respectively.
So of our 26 brands, 9 reported positive sales growth during the period of April to June 2025. These brands include Miu Miu, Brunello Cucinelli, Richemont Jewelry Maisons, Coach, Hermès, Stone Island, Ralph Lauren, Church’s, Tom Ford Fashions, and Zegna. The rest of the industry recorded negative growth with three brands (Stuart Wietzman, Thom Browne, and Gucci) recording 20+ percent declines in annual growth during the same period.

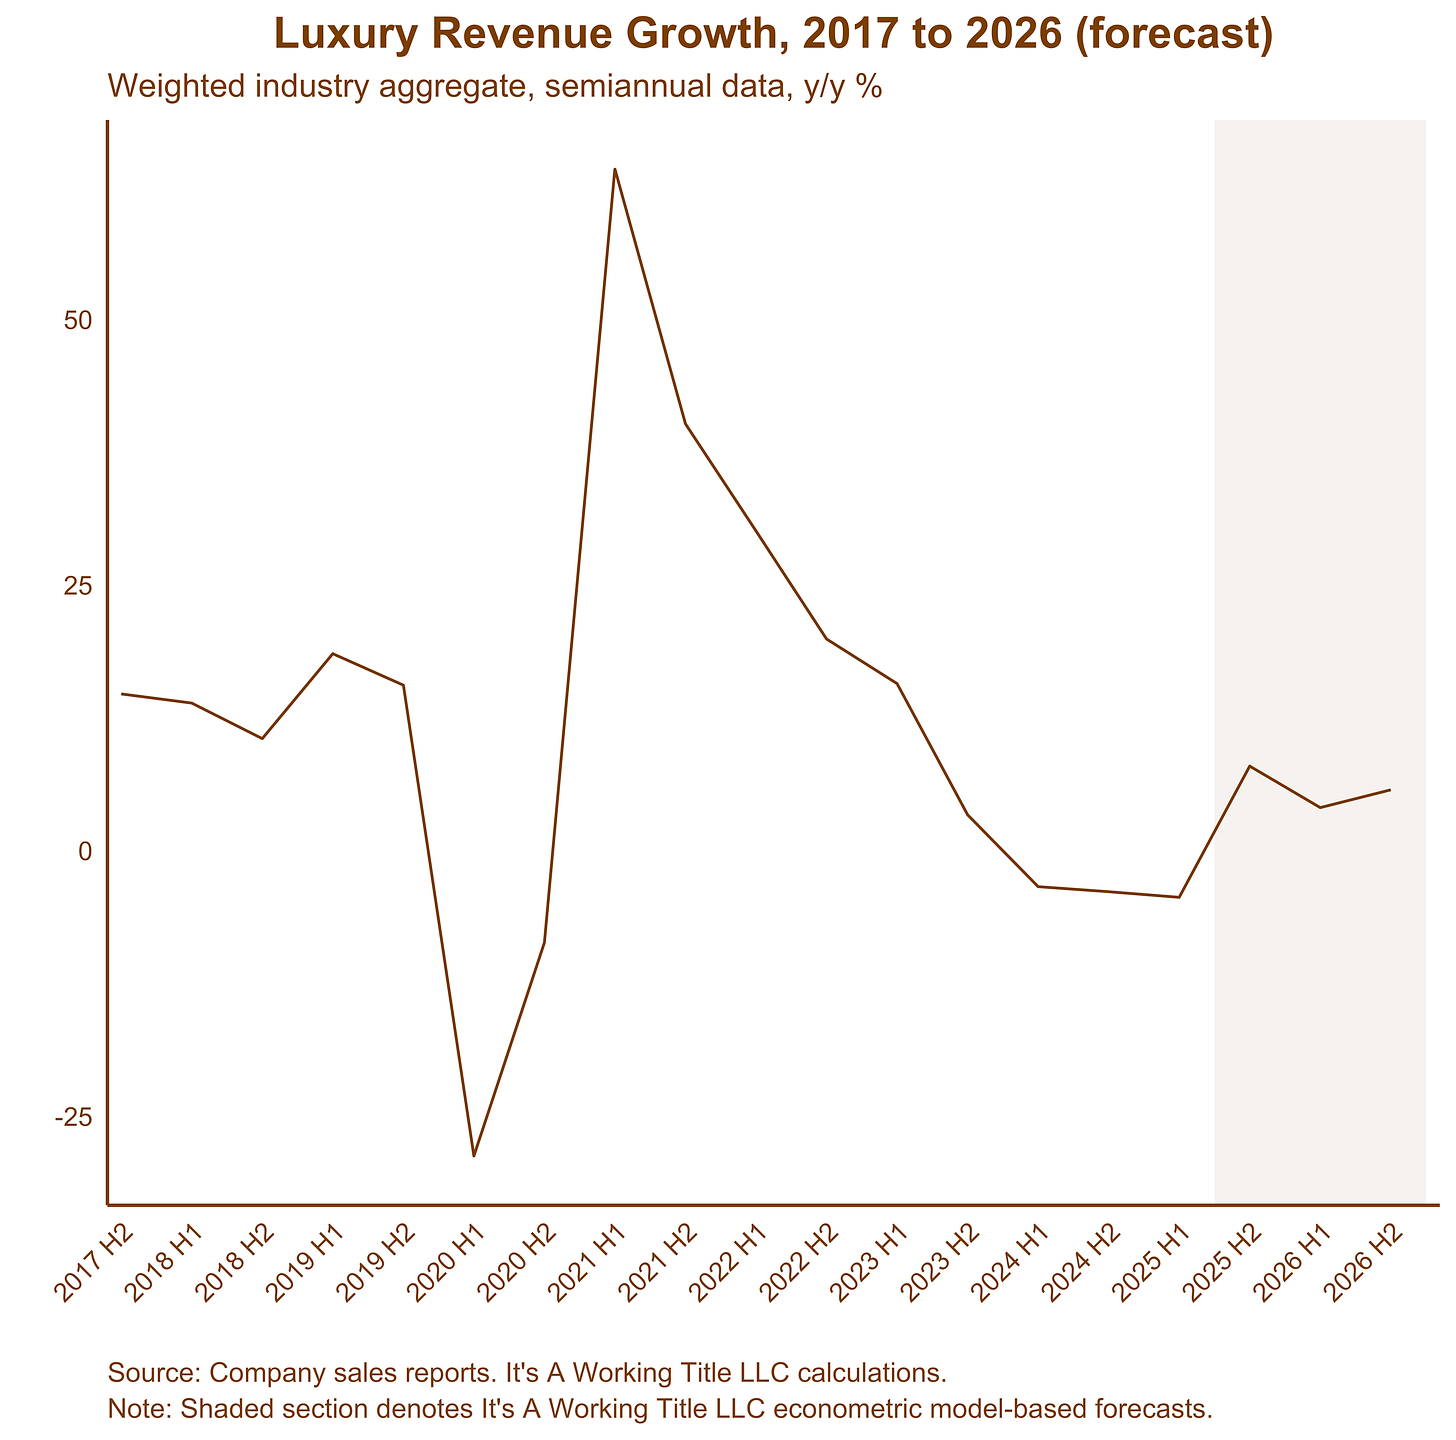
At the industry level, luxury remains in recession. The plot below shows annual revenue growth for a weighted index of major luxury organizations. The plot displays a fairly lengthy time series that encompasses semi-annual growth before, during, and after the pandemic, and includes the It’s A Working Title LLC industry forecasts for the period from H2 2025 to H2 2026. The industry has reported negative revenue growth for about six consecutive quarters. By our count, the only other instance of this occurrence was during and after the 2008 global financial crisis. This is a historically unique slowdown.
Yet, as we saw in the revenue numbers for the latest quarter, the slowdown is not universal. In fact, there has never been a period in recent history when performance by luxury brands has been so heterogeneous. To get a sense of the heightened level of dispersion in performance, we created a violin plot below, which illustrates how luxury firms’ revenue growth was distributed across the industry from 2017 to the latest results in 2025. The vertical axis shows revenue growth in percentage terms for the luxury firms in our sample, while the width of the “violin” indicates the number of firms with results at that level. Taller, stretched violins indicate that firms’ performances were more scattered, while shorter, wider ones suggest they were more similar. The violin for the last two quarters is the longest over this nine-year period of time, and the thinness shows that there is relatively low clustering of similar results.
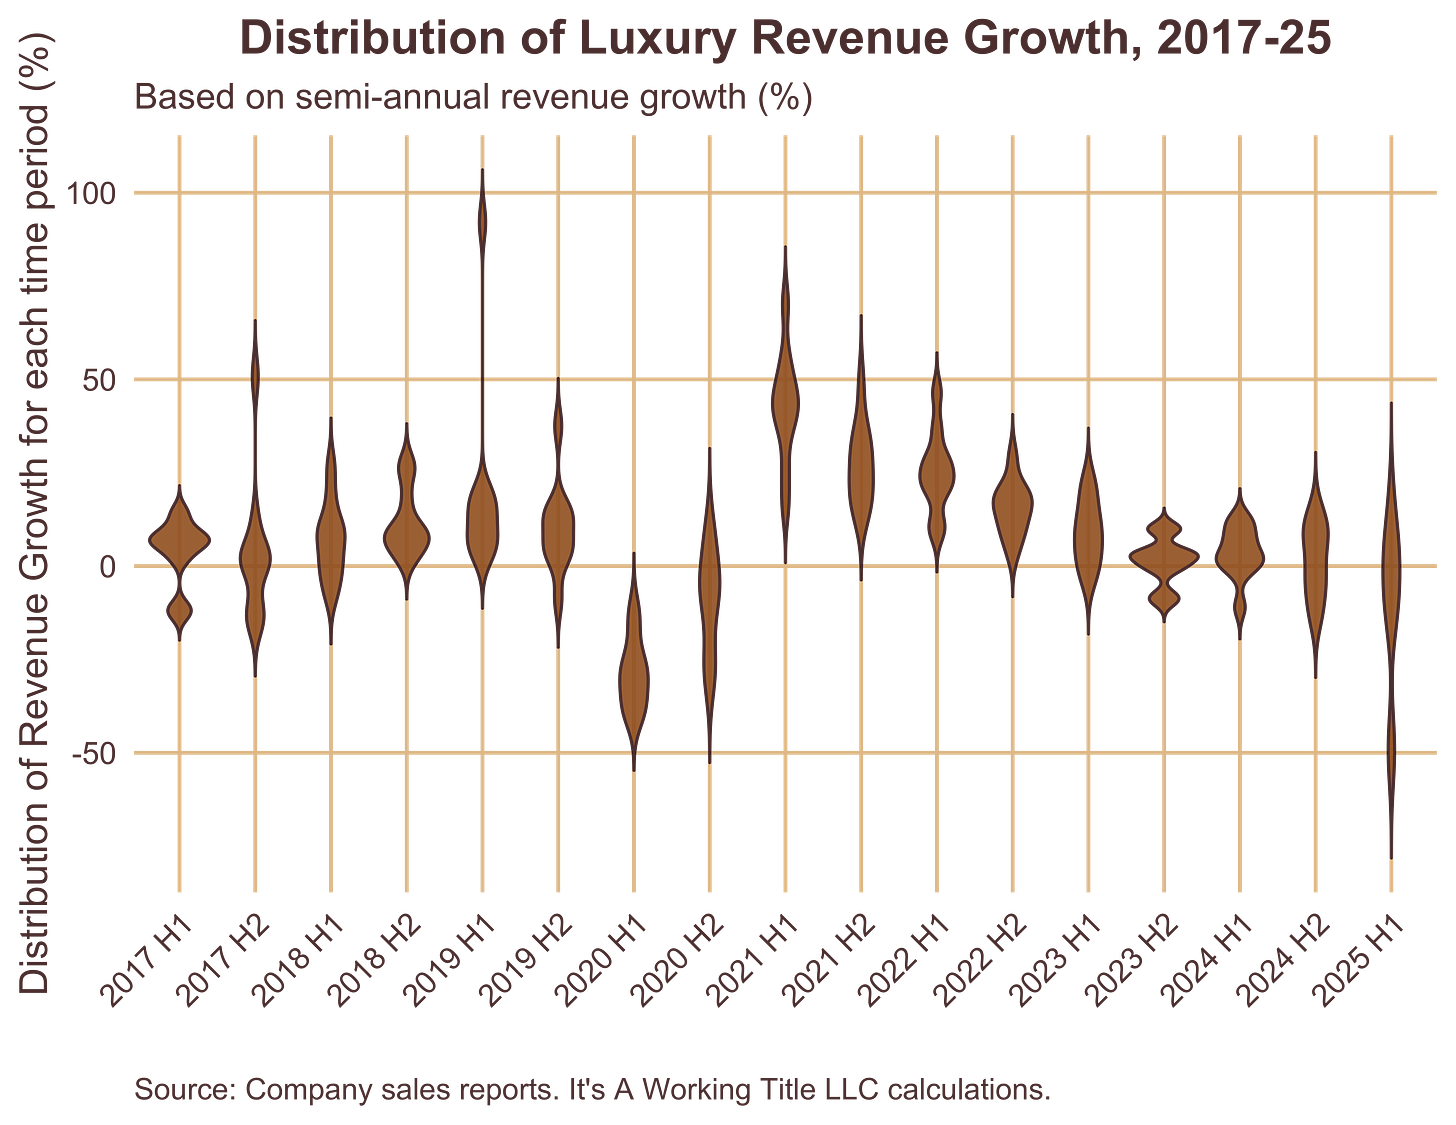
In fact since the pandemic, the volatility of luxury revenue growth has risen dramatically. Some standard measures of statistical variance point to this trend. The standard deviation of revenues, which shows the absolute spread of results, jumped from about 8–10 percentage points before 2019 to regularly above 20 and even into the 40s in recent periods. The coefficient of variation, which measures volatility relative to average growth, has spiked erratically since COVID—rising from around 0.7–1.0 before 2019 to levels above 2.0 and even near 4.0 in some recent half-years—showing that even strong years came with unstable performance. Meanwhile, the interquartile range—the spread between the middle 50 percent of firms—has widened from roughly 5–7 percentage points in the late 2010s to more than 12–13 percentage points after 2020, signaling that dispersion is no longer confined to a few outliers but now affects the core of the industry.