
The luxury industry seems to have broken its losing streak in late 2025. After six consecutive quarters of negative sales growth, earnings data for the three months ending in September point to very slight positive growth. Depending on what organisations/brands you include in your sample, how you weight it, and what definition of ‘revenue’ you use, you can get estimates between 0.01 and 0.4 percent growth or so. This does not signal an abrupt regime shift, but it may give some hope as a signal of stabilisation after the longest industry recession since the 2008 Global Financial Crisis. Using our econometric model-based forecasts, we expect industry growth to remain relatively weak, by historical standards, though positive for 2026 and 2027.

Yet, while most of the narrative around luxury for the past couple of years has been about a slowdown, the real story has been one of historically high differentiation. Some segments of the industry (for instance, beauty and wellness, travel and hospitality, and some automobiles) have exhibited resilience, while large segments of the fashion, leather goods, and wine and spirits businesses have struggled. But even among those luxury segments in recession, there has been a historically high degree of differentiated performance between winners and losers.
In fact, there has never been a period in recent history when performance by luxury brands has been so heterogeneous. To get a sense of the heightened level of dispersion in performance, we created a violin plot below, which illustrates how luxury firms’ revenue growth was distributed across the industry from 2017 to the latest results in 2025. The vertical axis shows revenue growth as a percentage for the luxury firms in our sample, while the width of the “violin” indicates the number of firms with results at that level. Taller, stretched violins indicate that firms’ performances were more scattered, while shorter, wider ones suggest they were more similar. The violin for the last two quarters is the longest over this nine-year period, and its thinness indicates relatively low clustering of similar results.

In fact since the pandemic, the volatility of luxury revenue growth has risen dramatically. Some standard measures of statistical variance point to this trend. The standard deviation of revenues, which shows the absolute spread of results, jumped from about 8–10 percentage points before 2019 to regularly above 20 and even into the 40s in recent periods. The coefficient of variation, which measures volatility relative to average growth, has spiked erratically since COVID—rising from around 0.7–1.0 before 2019 to levels above 2.0 and even near 4.0 in some recent half-years—showing that even strong years came with unstable performance. Meanwhile, the interquartile range—the spread between the middle 50 percent of firms—has widened from roughly 5–7 percentage points in the late 2010s to more than 12–13 percentage points after 2020, signalling that dispersion is no longer confined to a few outliers but now affects the core of the industry.
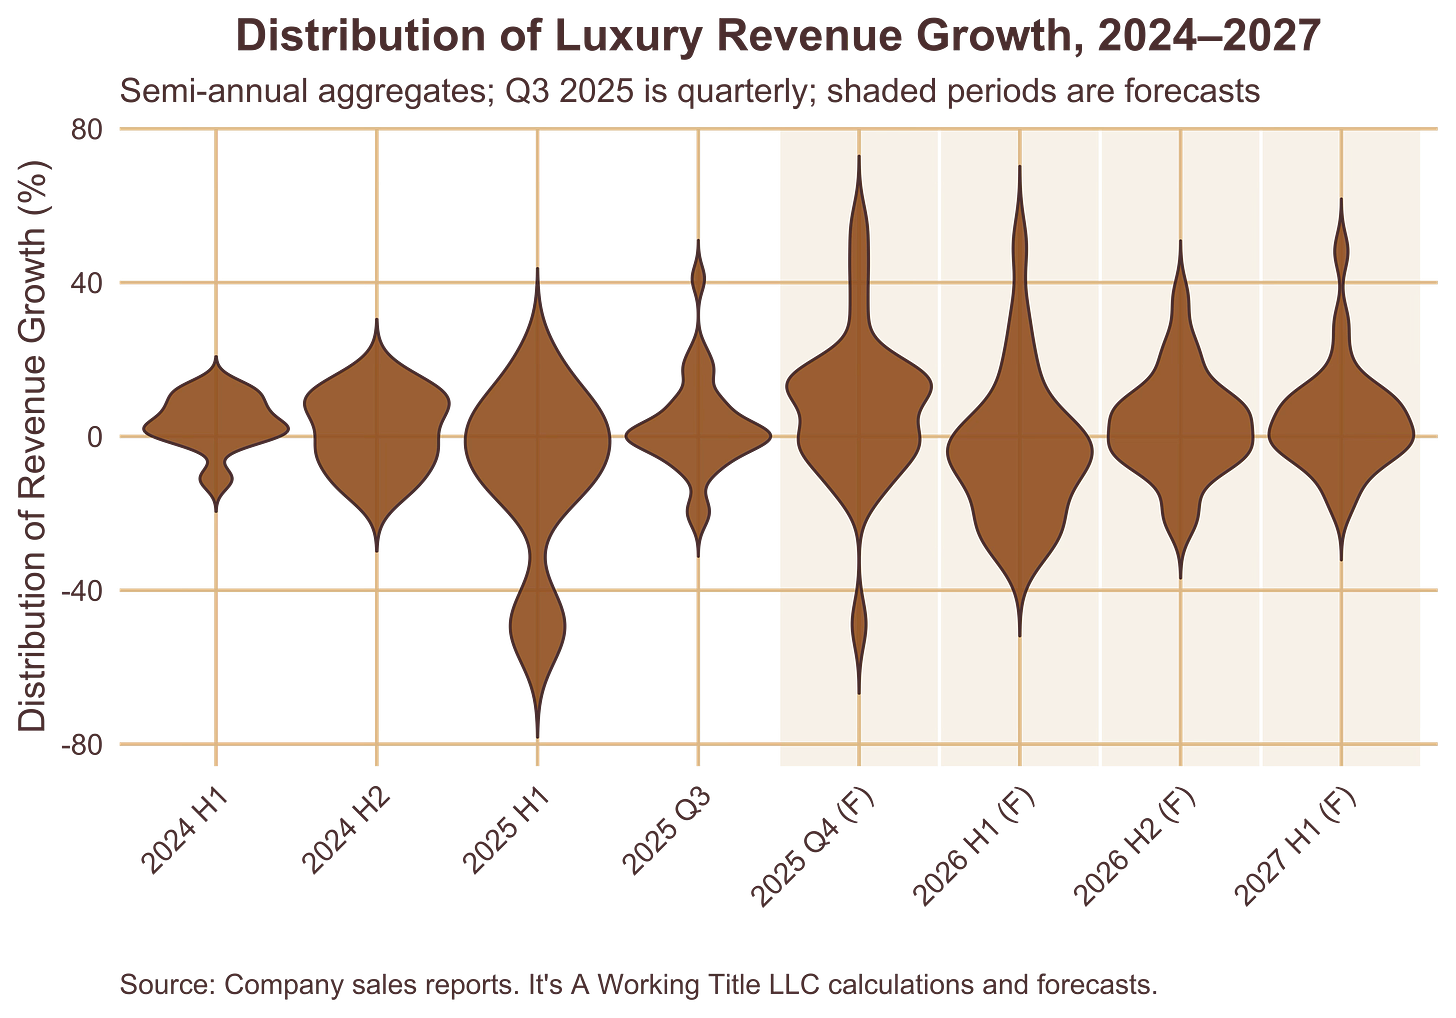
Our forecast is that differentiation will remain pronounced for the next two years, though it will come off its historic highs. The below figure exhibits our violin plots for 2024 and H1 2025 with forecasts for the fourth quarter of 2025 and semiannual forecasts for 2026 and 2027. We expect the standard deviation to decline from 21.9 in full-year 2025 to 17.4 this year and 13.1 next year. The coefficient of variation will decline from 2.3 in 2025 to 1.2 in 2027 while the interquartile range should drop from 26.1 to 14.6 during the same period. So we should start to see more cross-industry convergence as the broader industry emerges from recession, as we have predicted. But differentiation will remain above historical norms. What drives this unique period of differentiated performance across the luxury business?