
The luxury industry appears to have broken its losing streak. After six consecutive quarters of negative sales growth, earnings data for the three months ending in September point to very slight positive growth. Depending on what organisations/brands you include in your sample, how you weight it, and what definition of ‘revenue’ you use, you can get estimates between 0.01 and 0.4 percent growth or so. This does not signal an abrupt regime shift, but it may give some hope as a signal of stabilisation after the longest industry recession since the 2008 Global Financial Crisis.

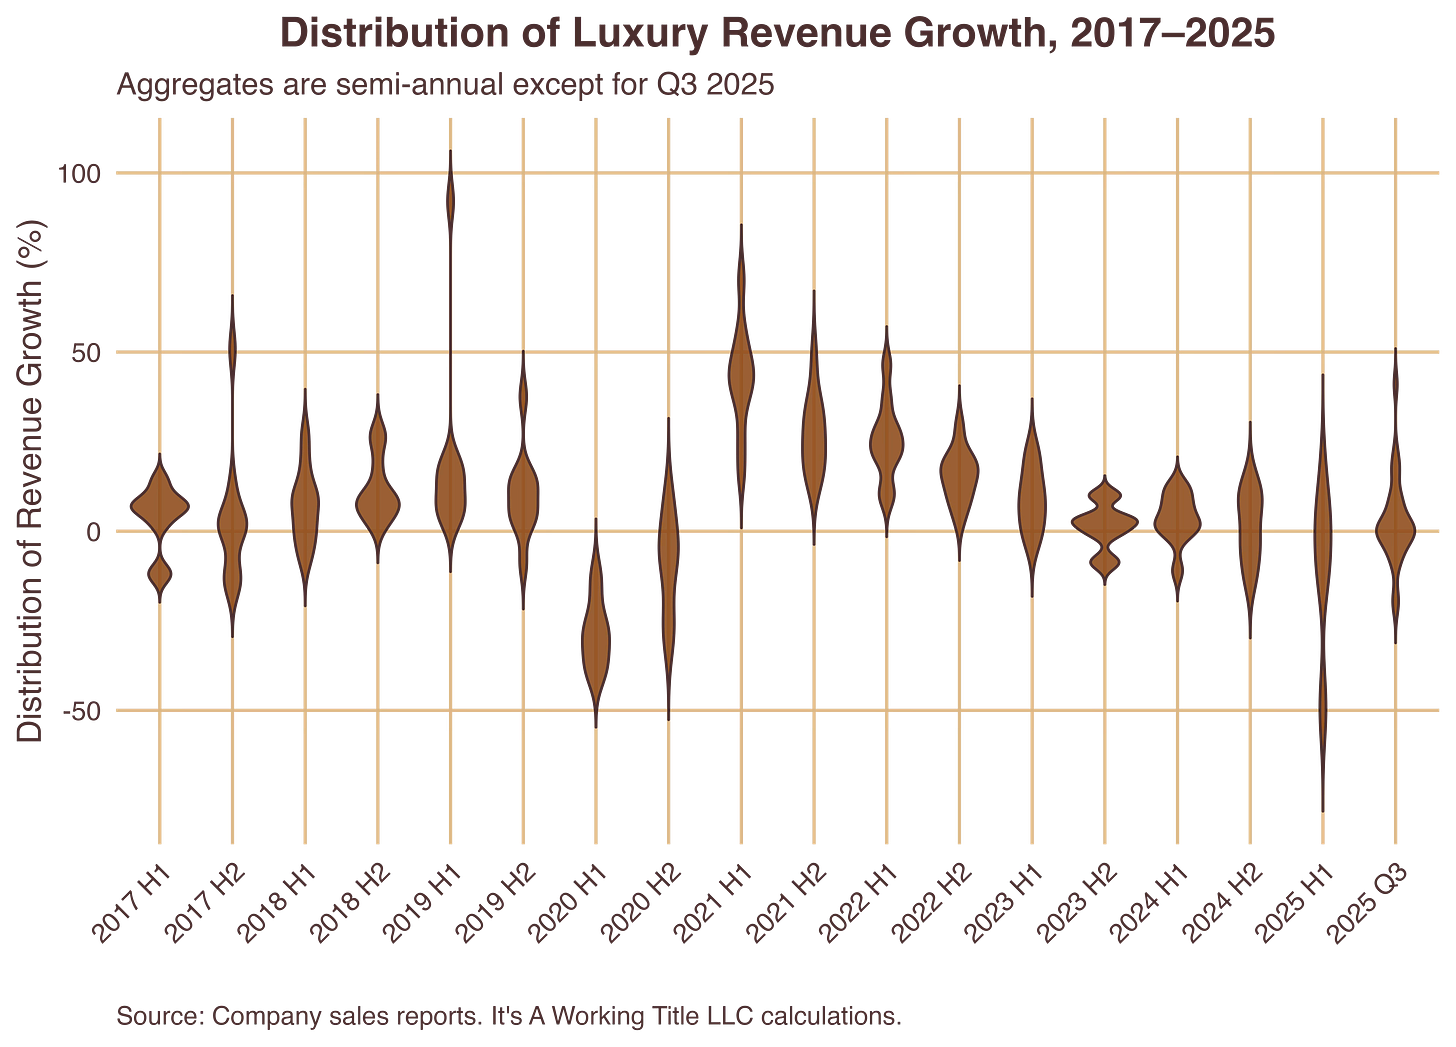
As always, weighted averages and other central tendencies hide significant variation in performance across the industry. As we discussed in our September 2025 industry macro overview (Why Some Luxury Brands Continue to Grow in this Market), this luxury recession has been accompanied by the highest level of differentiated performance across brands that our data sources could pin down: the coefficient of variation jumped from around 0.7 in the 10 years before the pandemic to nearly 4.0 in this recession. However, as the below ‘violin plot’ exhibits, there is more industry compression in the latest quarter.
The chart below shows year-over-year revenue growth for 26 brands (or quasi-brands in the case of the LVMH and Richemont product aggregates, which we use since these conglomerates do not report brand-level data) for the July to September (brown bar) and April to June (yellow dot) periods of this year. In the most recent quarter, 14 of the 26 brands reported positive sales growth, compared with 9 in the previous quarter. Some of the top performers continued to report consistent growth (Miu Miu) or even stronger growth in the last quarter (Coach, Richemont Jewelry Maisons, and Ralph Lauren). Six brands that reported negative growth the last time round returned to the black (Kate Spade, Richemont Specialist Watchmakers, LVMH Watches & Jewelry, LVMH Perfumes & Cosmetics, Burberry, and Boss). Gucci and the transitioning Versace continued to earn the wooden spoon, though even most of the weaker performers have improved in the recent quarter (Gucci, Thom Browne, Saint Laurent, Jimmy Choo, LVMH Fashion & Leather, and Michael Kors).
At the regional level, the turnaround in Asia has been the biggest surprise, while consumers in the Americas continue to anchor the luxury goods business. The slowing of economic growth, and in particular private consumption, in China has been a major driver of the industry recession. Onshore Chinese luxury spending has been a major driver of the industry’s growth and evolving character over the past 15 years. So the turnaround from negative annual growth to positive, albeit very small, from July to September may represent an important leading indicator of a turning point. If macroeconomic forecasts for China’s annual GDP growth over the next year are to be believed (and, by and large, these types of projections tend to be wrong), hopes for greater onshore China luxury consumption will need to hope that there is a growing propensity to spend on luxury from a mostly unchanged rate of economic growth. The IMF’s latest forecasts are for China’s economy to grow by 4.2 percent in 20265, which 0.8 percentage points slower than it was in 2024.

